Commercial Law

Mediation vs Court – which is better?

When a dispute arises, many people assume that going to Court is the only way to resolve it. In reality, most commercial, property, estate and business disputes are resolved without a Judge ever making a decision.

One of the most common alternatives to Court is mediation. So, which option is better? The answer depends on the circumstances, but in most cases mediation should be seriously considered before proceeding to file an action in a Court.

WHAT IS MEDIATION?

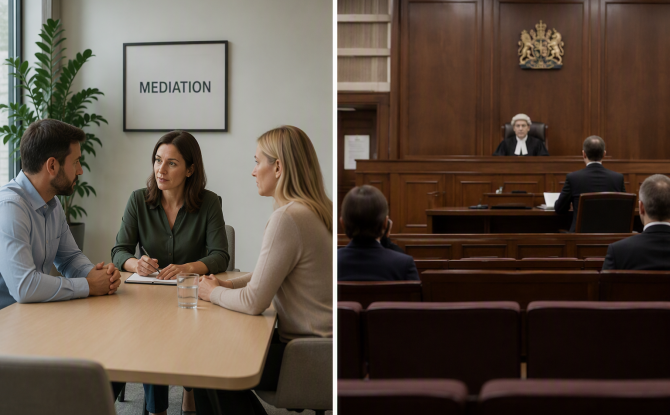
Mediation is a structured negotiation process in which an independent third party (mediator) assists the parties to the dispute to reach a mutually acceptable resolution.

Importantly, the mediator doesn’t decide who is right or wrong and does not impose a decision. Instead, they help the parties identify issues, explore options and negotiate a settlement.

Mediations can occur:

  • before Court proceedings commence;
  • during litigation;
  • as a result of a Court order; or
  • as part of dispute resolution procedures agreed by parties beforehand in their contract.

If an agreement is reached at the mediation, the terms are usually documented in a binding settlement agreement.

WHAT DOES LITIGATION ENTAIL?

Litigation involves a Court or Tribunal determining a dispute according to the law and evidence presented by the parties.

The process will generally involve:

  • Pleadings (formal documents like Summons, Statement of Claim etc filed with the Court);
  • Evidence (Affidavits – formal sworn witness statements);
  • Subpoenas and Discovery (production of documents);
  • Interlocutory applications (for procedural orders or specific pre trial issues);
  • Hearing – where the Judge delivers a judgment.

Unlike mediation, a Judge makes the decision and the parties generally lose control over the outcome. Plus, the usual order is that “costs follow the cause” so if you lose, you pay the other parties’ legal costs as well as your own.

ADVANTAGES OF MEDIATION

Mediation offers several advantages to going to Court, including:

Lower cost – Litigation can be expensive. Legal costs can quickly increase as the matter progresses through pleadings, evidence, conferences and hearings. Mediation often resolves disputes before significant legal costs are incurred.

Faster resolution – Court proceedings can take many months or even years to reach a final hearing. A mediation can often be arranged within weeks and often are resolved in a single day.

Greater control – In mediation, the parties control the outcome. Rather than having a Judge impose a decision, the parties can negotiate a practical solution that suits their particular circumstances.

Confidentiality – Court proceedings are generally public. Mediation discussions are usually confidential and conducted on a “without prejudice“ basis, allowing parties to negotiate openly without fear that settlement discussions will later be used against them.

Preservation of relationships – Business partners, family members, landlords and tenants often need an ongoing relationship after the dispute is resolved. Mediation is generally less adversarial than litigation and may help preserve commercial or personal relationships.

COURT PROCEEDINGS CAN PROVIDE ADVANTAGES

Advantages of heading to Court, include:

A binding determination – Where parties are unable or unwilling to compromise, Court provides a final determination. The Judge’s decision is legally binding and enforceable.

Urgent relief – Courts can grant injunctions and other urgent orders where immediate action is required to protect assets, preserve evidence or prevent further loss.

Compulsory powers – Courts have powers that mediators do not. For example, Courts can:

  • compel the production of documents (Discovery, Subpoena or Notice to Produce);
  • require witnesses to attend (through Subpoenas or Notices to Attend);
  • make enforceable Orders; and
  • award damages and costs.

Establishing legal rights – Sometimes a party needs a clear legal ruling, particularly where an important principle or contractual interpretation is in dispute. In these cases, litigation may be unavoidable.

WHEN IS MEDIATION LIKELY TO BE BETTER?

Mediation may be particularly suitable where:

  • both parties are willing to negotiate;
  • the parties wish to maintain an ongoing relationship;
  • confidentiality is important;
  • the legal costs of litigation are disproportionate to the amount in dispute; or
  • a practical solution is more important than a legal victory.

Examples of where mediations can generally assist include:

It is important to understand however, that mediation and Court are not mutually exclusive. Many disputes commence in Court and are later referred to mediation. In fact, a large proportion of civil disputes settle at mediation after the parties have exchanged evidence and have a better understanding of the strengths and weaknesses of their respective positions.

Often, commencing proceedings can provide the leverage necessary to bring the parties to the negotiating table. The best approach depends upon the nature of the dispute, the issues involved and the attitude of the parties. Obtaining early legal advice can help identify the most effective strategy and may save considerable time and cost.

FURTHER INFORMATION

Contact McKillop Legal for further information regarding commercial disputes, litigation, mediation, debt recovery or dispute resolution, contact McKillop Legal on (02) 9521 2455 or email help@mckilloplegal.com.au.

This article is general information only and is not legal advice. Specific advice should be obtained for your individual circumstances.
Late payments – is your business protected?

For many small and medium-sized businesses, the biggest threat to profitability (and sustainability) is not a lack of work, it is getting paid on time.

Cash flow problems caused by overdue accounts can affect the ability of a business to pay suppliers, meet payroll obligations, invest in growth and maintain profitability. If one business fails, that has consequences for other businesses, creating a domino of insolvencies and it is particularly catastrophic when owners or directors have personally guaranteed the debts of the business.

While good commercial relationships are important, businesses should also ensure they have the right legal protections in place before problems arise.

PREVENTION IS BETTER THAN RECOVERY

The easiest debt to recover is the one that was properly documented from the beginning.

Many businesses still rely on verbal agreements, email exchanges or informal quotes when supplying goods or services. Unfortunately, these arrangements can become difficult to enforce if a dispute arises.

Well drafted T&Cs should clearly address matters such as:

  • payment terms;
  • interest on overdue accounts;
  • retention of title;
  • limitation of liability;
  • dispute resolution procedures;
  • recovery of legal costs; and
  • termination rights on default.

Having these provisions in writing can significantly strengthen your legal position if payment is not made.

Many businesses have not reviewed their trading terms (if they even have them) for several years. Changes in legislation, court decisions and business practices mean that outdated contracts may no longer provide the level of protection they once did.

A regular legal review can identify gaps before they become expensive disputes.

IT PAYS TO ACT EARLY

One of the most common mistakes businesses make is waiting too long before taking action. Early intervention often results in quicker resolution and lower recovery costs.

The longer an account remains unpaid, the less likely it is to be recovered. Businesses should have clear internal credit control procedures, including:

  • issuing invoices promptly;
  • following up overdue accounts consistently;
  • sending formal letters of demand where appropriate; and
  • obtaining legal advice before debts become difficult to recover.

DIRECTOR DUTIES

For company directors, cash flow issues can create additional legal risks. Continuing to incur debts when a company is unable to pay its existing liabilities may expose directors to claims relating to insolvent trading under the Corporations Act 2001 (Cth) and breach of other director duties.

Directors experiencing financial pressure should seek professional legal and accounting advice as early as possible. Early restructuring or negotiated commercial solutions are almost always preferable to allowing financial difficulties to escalate.

STRONG CONTRACTS PROTECT MORE THAN CASHFLOW

Commercial contracts do much more than record the agreed price. Well-prepared agreements can reduce misunderstandings, allocate risk appropriately, establish clear dispute resolution processes and protect valuable business relationships.

Whether you are engaging contractors, supplying goods, providing professional services or entering long-term commercial arrangements, investing in professionally drafted agreements is often far less expensive than resolving disputes after they arise.

HOW WE CAN HELP

Every business is different, and contracts should reflect the specific risks of your industry.

The McKillop Legal team assists businesses with:

A proactive legal review today can help prevent costly disputes tomorrow.

This information is general only and is not a substitute for proper legal advice. Please contact McKillop Legal to discuss your legal concerns or objectives.

Card payment surcharge ban

Businesses incur costs for processing certain card payment types. Some businesses typically included these costs in the prices they charged for their products, whilst others passed on the costs for paying with a card as a “surcharge“. From 01 October 2026, this all changes and no surcharges are payable at all.

Many card payment facilitators (such as Stripe) charge businesses that use their service differently depending on the card used. For example, domestic cards within Australia such as Visa and Mastercard may be processed at 1.8% plus 30c per transaction whereas international cards like American Express may be processed at 3.5% plus 30c per transaction (excluding the cost of any currency conversion, if required).

Previously, the rules that applied when a business applies a surcharge to particular cards included:

  • the surcharge can only include costs that are for accepting that payment type and the surcharge must not have been more than what it actually costs the business to process that payment type
  • if there was no way for a consumer to pay without paying a surcharge (for example debit/credit card only transactions), the business must include the minimum surcharge payable in the displayed price for its products. (If customers paid by cash, direct transfer or cheque, then this isn’t required)
  • if a business charged different surcharge amounts for different card types, they must have clearly displayed the higher surcharges for other card types.
  • If a business could charge the same fee they are charged for each card type (for example the 1.8% for Visa and 3.5% for AMEX above), but rather imposed one standard level of surcharge for all card types, they could only charge the lowest possible surcharge (being 1.8%)

From 01 October 2026, businesses must not pass on any surcharge for accepting payment via EFPTOS, Visa or Mastercard and instead must absorb the cost. Payment via BPAY, PayPal or international cards like Diners Club, JCB or AMEX are excluded by these changes for now, with changes expected in April 2027.

Practically, this means that in the Reserve Bank of Australia’s push for transparency, consistency and simplicity, the costs for goods and services sold to consumers will simply be increased by most businesses as they adjust their pricing strategy to cover the shortfall caused by the inability to pass on the costs via a surcharge.

Businesses may also need to update their Terms of Trade accordingly.

FURTHER INFORMATION

Craig Pryor is principal solicitor at McKillop Legal. For further information in relation to the leasing or licensing of business premises, commercial law or business related matters, contact Craig Pryor on (02) 9521 2455 or email craig@mckilloplegal.com.au.

This information is general only and is not a substitute for proper legal advice. Please contact McKillop Legal to discuss your legal concerns or objectives.

Stay up to date – LinkedIn | Facebook | Twitter

Have you just been served?

COURT PAPERS JUST DELIVERED TO YOUR OFFICE?

If you have received a Statement of Claim, Summons, Originating Process or Writ, be aware that you must act very quickly.

Replying to the person, entity or firm that issued the Court/Tribunal papers is not enough. Formal steps to file an Appearance, Defence, Notice of Intention to Defend or Reply must be taken within the relevant time.

The proper form of response varies depending on which court and in which jurisdiction the proceedings have been commenced as they each have different Rules and Regulations that apply.

Generally, a Defendant, Respondent etc will have only 28 days or such other period as may be specified in the document in which to file the appropriate response. Failure to do so in time or at all will leave the recipient open to summary or default judgment (automatic judgment against you without a hearing).

Failure to file and serve the appropriate document in response in time can have dire consequences.

A judgment can affect credit ratings, the ability to seek finance in the future and is a precursor to enforcement actions such as bankruptcy litigation, liquidation and winding up of companies, garnishee orders, writs of possession, visits from the Sheriff, notices for examination etc!

Default judgments can often be set aside, but this comes at a cost and immediately puts you on the back foot. In litigation, it is best to stay ahead of the game and be pro-active.

Most court documents are required to be served personally however, companies can be served by post at their registered office. Documents commencing proceedings for small claims (claims under $10,000) can be served by post by the court.

If a court document is served, steps should be taken to immediately seek advice from (rather than leaving it to the last few days).

McKillop Legal can assist in various ways such as:

  • seeking more details of the claim from the lawyers for the party commencing the claim,
  • filing and serving the appropriate document to prevent default judgment,
  • advising on the claim and its prospects of success,
  • filing any defence document
  • preparing your evidence,
  • attempting to resolve the matter prior to any hearing, and/or
  • if necessary, running the hearing with a barrister.

FURTHER INFORMATION

For further information in relation to litigation and dispute resolution or any commercial law matter, contact McKillop Legal  on (02) 9521 2455 or email help@mckilloplegal.com.au.

Commercial Leases

A commercial lease, simply put is the agreement between the owner of business premises (the lessor) to the tenant that is to occupy those premises (the lessee).

The terms of each commercial lease can and usually do differ depending on the nature of the property, the location and the use to which the premises are to be put. There are however many terms that are common to all leases, even if they may be drafted differently in each lease document.

Sometimes confusion arises as to whether a lease is of commercial premises as opposed to retail premises. Retail leases are covered by the Retail Leases Act and there are many additional obligations on the Lessor in relation to retail premises such as the provision of a Disclosure Statement, minimum lease term etc

Prior to entering into a lease, it is a good idea to obtain a condition report or at least take photos or video to show the condition of the premises as at the commencement date and to show what fixtures and fittings were in place.

Some key considerations in relation to a business or commercial lease include:

  • Development consent for the intended use of the premises
  • Term
  • Options to renew or buy
  • Rent
  • The process for and timing of rent reviews (CPI, market, fixed increase etc)
  • Outgoings
  • Security bonds
  • Director guarantees
  • Costs
  • Insurances
  • Repair and maintenance obligations
  • Lessee’s make good and refurbishment obligations on termination
  • Any pre-lease works/promises made
  • Assignment and sub-letting/licensing

It is not uncommon for the parties to enter into a Heads of Agreement or similar document whereby some or all of the above matters and more are documented briefly, such that the key terms are signed off as agreed, but it is usually important to ensure that this document itself doesn’t create a lease and is in fact subject to the parties negotiating and signing a formal written Commercial Lease.

Leasing can be complicated so it pays to seek the advice of a lawyer before entering into a Commercial Lease, an Agreement for Lease or a Heads of Agreement.

FURTHER INFORMATION

For further information in relation to the leasing or licensing of business premises, commercial law or business related matters, contact McKillop Legal on (02) 9521 2455 or email help@mckilloplegal.com.au.

This information is general only and is not a substitute for proper legal advice. Please contact McKillop Legal to discuss your legal concerns or objectives.

Stay up to date – LinkedIn | Facebook | Twitter

What is a Buy/Sell Deed?

WHY HAVE A BUY/SELL DEED?

A Buy/Sell Deed is an agreement between the owners of a company or unit trust that upon the death or permanent disablement of a director or key person associated with a shareholder/unitholder, that shareholder/unitholder must transfer its shares to the remaining shareholders in exchange for payment.

The method of determining the price is agreed and the funding of that payment usually comes from the proceeds of insurance policies to be taken out for those risks by the shareholders/unitholders.

A Buy/Sell Agreement is not a general Shareholders Agreement or Unitholders Agreement, so it does not regulate all dealings in relation to the company (however the Buy/Sell obligations can be in such agreements rather than in a separate document).

COMMON SCENARIOS A BUY/SELL DEED COULD HELP PREVENT

Consider the following and how it may affect you and your company…

  • A shareholder dies and you as the remaining shareholder inherit an unintended (and potentially non-income producing) business partner such as the deceased shareholder’s spouse (as they receive the deceased’s assets via their Will or intestacy), with company profits being paid out according to the respective shareholdings.
  • You have to buy shares from a deceased shareholder’s estate above their value.
  • Your family do not get the best price for your shares in the company.
  • The remaining shareholders don’t have available funds to pay out a deceased shareholder or a shareholder who can no longer contribute to the business due to total and permanent disability.
  • The business either needs to be sold or funds need to be borrowed by the remaining shareholders or the company to make the payments.
  • A key person to the company has died, leaving the company in the position of losing a key source of revenue, client relationships and knowhow, affecting the value of the company and its business and its viability in the future.

CERTAINTY

A Buy/Sell Agreement is designed to bring certainty in relation to the exit from a business as the result of death or permanent disability of a key person – certainty for an ill shareholder, a deceased shareholder’s family, the remaining owners and the company itself. Don’t leave it to chance.

FURTHER INFORMATION

Craig Pryor is principal solicitor at McKillop Legal. For further information in relation to Buy/Sell Deeds, Shareholders Agreements, any or any commercial dispute or issue, contact Craig Pryor on (02) 9521 2455 or email help@mckilloplegal.com.au.

This information is general only and is not a substitute for proper legal advice. Please contact McKillop Legal to discuss your legal concerns or objectives.

Stay up to date – LinkedIn| Facebook | Twitter | McKillop Legal Blog

All employers now subject to employee “right to disconnect”

Whilst it isn’t news that, under amendments to the Fair Work Act 2009 (Cth) (FW Act) and consequent amendments to Modern Awards, from 26 August 2024 employees of larger employers have the new ‘right to disconnect’ outside of work hours… what many small businesses employers don’t realise is that this law will also apply to them from 26 August 2025.

What is a “small business employer”?

A small business employer is an employer with fewer than 15 employees at a particular time.

When counting the number of employees, employees of associated entities of the employer are also included. Casual employees are not included in this headcount unless they are engaged on a regular and systematic basis (but they also have the right to disconnect).

So what is the “right to disconnect”?

Employees have the right to refuse contact outside their working hours unless that refusal is unreasonable. This right means an employee can refuse to monitor, read or respond to contact from an employer or a third party (such as customers, clients, suppliers and related businesses) outside of an employee’s working hours.

Contact is broad and can include in person contact, calls, emails, texts, WhatsApp chats or through other Apps etc.

The right to disconnect is a protected right all employees have under the FW Act. An employee can’t be punished or adversely treated for enforcing a workplace right. Employees are protected from any disciplinary action for reasonably ignoring such emails.

What is “unreasonable”?

When working out whether an employee’s refusal is “unreasonable” other matters may also be considered but the following factors must be considered:

  • the reason for the contact
  • how the contact is made and how disruptive it is to the employee
  • how much the employee is compensated or paid extra for:
    • being available to perform work during the period they’re contacted, or
    • working additional hours outside their ordinary hours of work
  • the employee’s role in the business and level of responsibility
  • the employee’s personal circumstances, including family or caring responsibilities.

It will be unreasonable for an employee to refuse to read, monitor or respond if the contact or attempted contact is required by law.

Importantly, employers are not prohibited from initiating contact with employees, but the employee is not obliged to respond unless it is deemed ‘reasonable’ for them to do so.

Senior employees on large salaries will have limited access to this right as their role or remuneration already will likely include ‘reasonable additional hours’. These laws are mainly for the benefit of Award and lower level employees and those who are expected to be available on call without additional compensation.

Disputes

Disputes about an employee’s right to disconnect should first be discussed and resolved at the workplace level (s.333N).

If that isn’t possible, employees or employers can go to the Fair Work Commission (FWC) to deal with a dispute (s.333P).

The FWC can:

  • make a stop order
  • deal with the dispute in other ways (for example, by holding a conference to try to resolve the dispute), or
  • both.

FURTHER INFORMATION

For further information in relation to business succession, estate planning, litigation and dispute resolution or any commercial law matter, contact McKillop Legal on (02) 9521 2455 or email help@mckilloplegal.com.au

This information is general only and is not a substitute for proper legal advice. Please contact McKillop Legal to discuss your commercial law needs.

Stay up to date – LinkedIn | Facebook | Instagram

Who gets your Superannuation when you die?

On your death, your superannuation balance will not necessarily be dealt with in accordance with your wishes as stated in your Will. Read that again… slowly, then read on.

Unless you have a valid beneficiary death benefit nomination in place that directs your superannuation fund’s trustee as to who to pay your super balance to, your trustee may have a discretion as to who to pay it to.

The trustees of most retail super funds have a discretion as to who to pay a benefit to. Usually, the fund rules specify the member’s dependents as the class of beneficiaries to be considered first, with the trustee to determine the amounts/proportions but imagine what happens if you are perhaps separated (but not divorced) and you are living with another person (as a de facto) – a dispute could easily arise. What if you have children? What would/should the split be?

To minimise disputes and avoid applications to the Superannuation Complaints Tribunal or the Supreme Court, make a nomination. There are generally 2 types: Non-binding and Binding

NON-BINDING NOMINATIONS

A non-binding nomination is an indication to your trustee of your preferences but it is, as it states – non-binding so the trustee can ignore it. This can be a good idea if there are significant changes in circumstances before your death where you haven’t got around to updating your nomination. The trustee’s discretion could prevent it going to your ex spouse or avoid the situation of you accidentally omitting one of your kids from a benefit.

BINDING NOMINATIONS

A binding nomination is exactly that – binding (provided that it is valid as at the date of death). There are 2 sub-categories of binding nomination: lapsing and non-lapsing.

  • LAPSING – Many funds provide for the lapsing type – and unfortunately these need to be renewed every 3 years or the nominations lapse.
  • NON-LAPSING – Most Self-Managed Super Funds (SMSFs) and some retails funds allow in their deeds for nominations that never lapse (unless you update it). Older SMSF Deeds and their Rules do not allow for the non-lapsing type and may need to be updated.

There are requirements for making any nomination legally valid, witnesses etc.

Speak to us about your estate planning and ensure your wishes are properly documented.

FURTHER INFORMATION

If you would like any further information in relation to Wills, estate planning, superannuation death benefit nominations or updating SMSF deeds , please contact us on (02) 9521 2455 or email help@mckilloplegal.com.au

What is an Injunction?

An injunction is a Court order directing a person or entity to do a specific thing or not to do a something.

Most injunctions are temporary and are often made pending the outcome of a full hearing (known as an “interlocutory injunction“). An example may be to restrain a former employee from doing work for former clients where they have agreed to post-employment restraints pending a hearing on whether the restraint is lawful or to prohibit the publication of a potentially defamatory article in a newspaper or television program.

A Court will not grant an interlocutory injunction unless:

  • the Plaintiff has made out a “prima facie” case – a sufficient likelihood of success to justify in the circumstances the preservation of the status quo pending the trial – or established that there is a serious question to be heard;
  • the balance of convenience favours the granting of the injunction; and
  • the Plaintiff provides “the usual undertaking as to damages” (that they will pay any damages the restrained party suffers if at a final hearing the Court determines that the injunction wasn’t justified).

A Court has discretion as to whether to make such an order and will consider thongs like whether or not you have asked the other party to do/not do the relevant thing, whether damages would be an appropriate remedy, if you have waited too long to seek the order etc.

Where an injunction is sought from a Court without the affected party being notified, this is known as an “ex-parte injunction” as it is made in the absence of a party. They are for that reason only temporary and the Court requires the applicant to disclose all relevant facts to the case, including those that may lead to refusal of the application, not just those in favour of the injunction as there is no respondent in Court to oppose it. Examples can be “freezing orders” that stop the sale of assets or to freeze a bank account to preserve them pending the Court’s further orders.

Mandatory injunctions can be obtained where for example a party to a contract refuses to comply with their lawful obligations under it. An example of this is a party to a Contract for the Sale of Land that unlawfully refuses to sign a Transfer in registrable form. Such an injunction imposes a positive obligation on the affected party to do something, not just stopping them from doing something.

FURTHER INFORMATION

For further information in relation to business succession, estate planning, litigation and dispute resolution or any commercial law matter, contact McKillop Legal on (02) 9521 2455 or email help@mckilloplegal.com.au

This information is general only and is not a substitute for proper legal advice. Please contact McKillop Legal to discuss your commercial law needs.

Stay up to date – LinkedIn | Facebook | Instagram

Why updating ASIC records is critical

Under the Corporations Act 2001 (Cth), among other methods, any document may be served on a company by:

(a) leaving it at, or posting it to, the company’s registered office; or

(b) delivering a copy of the document personally to a director.

This means that ASIC, the ATO, other government authorities or any other creditor can serve important papers on a company at its former place of business (where that address has not been updated at ASIC) even if they have since moved.

Documents that could be served on a company can include:

  • Court proceedings such as an Originating Process / Statement of Claim / Summons

As these important documents can be served on a company even though they may not actually come to the attention of the company or its directors, demonstrates why updating ASIC records is critical.

Similarly, if the ATO was to serve a Director Penalty Notice (DPN) on a director, note that:

  • DPNs are sent via ordinary mail to the Director’s last recorded residential address on ASIC’s database
  • notice is given on the day the DPN is issued, not when it is or is likely to have been received
  • actual non-receipt of a DPN is not a defence.

FURTHER INFORMATION

For further information, please contact McKillop Legal on (02) 9521 2455 or email help@mckilloplegal.com.au 

This information is general only and is not a substitute for proper legal advice. Please contact McKillop Legal to discuss your needs.